Modexus Targets Up to 55% Revenue CAGR on AI Cooling Boom and $500M Buyback
Modexus Solutions projects up to 55% revenue CAGR through fiscal 2029 on booming data center cooling demand, backing its growth with a $500M buyback.
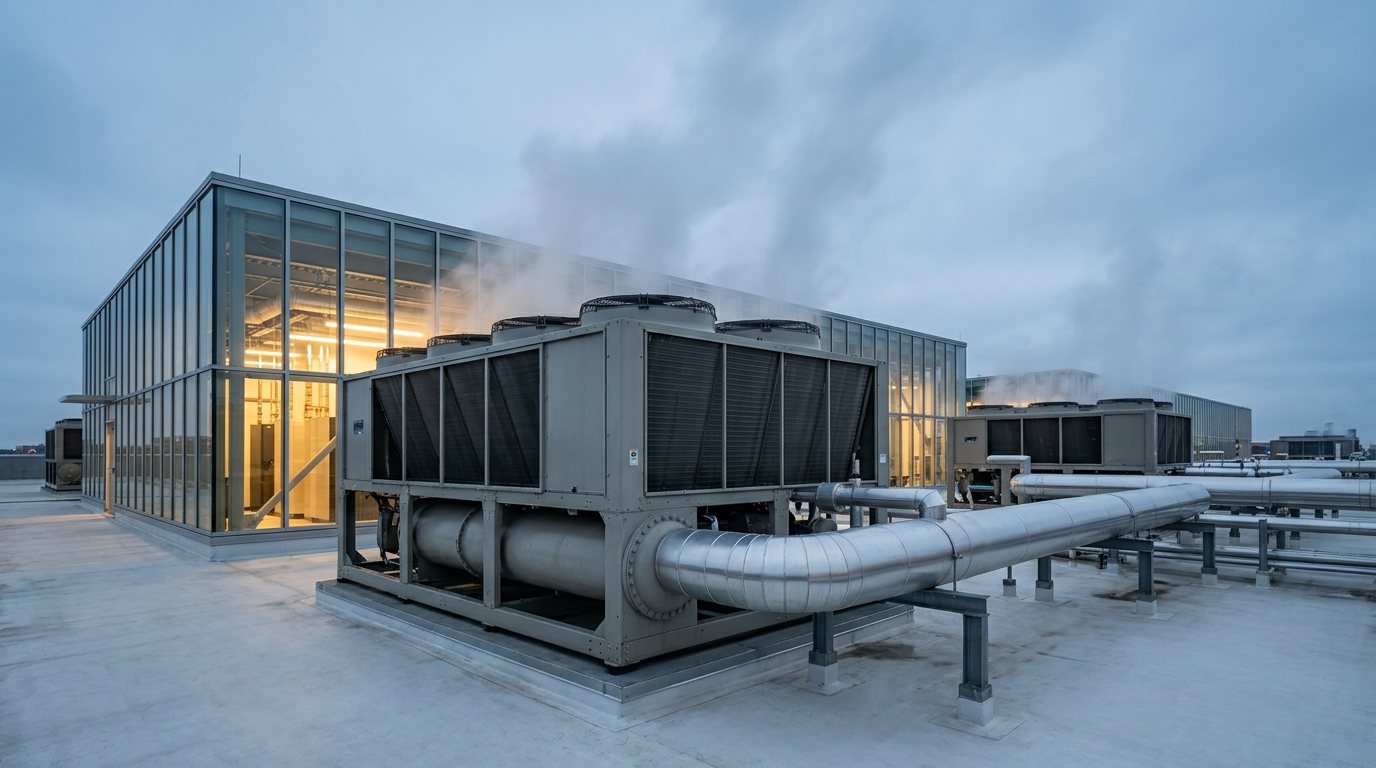
Modexus Solutions (NYSE: MOD), formerly Modine Manufacturing, unveiled aggressive fiscal 2029 financial targets at its Chicago Investor Day on Wednesday, projecting a 40% to 55% three-year revenue compound annual growth rate alongside a fresh $500 million share repurchase program. The ambitious outlook signals that the newly transformed thermal management specialist is positioning itself as an indispensable hardware pure-play for power-dense artificial intelligence infrastructure.
What happened
Fresh off its November 16 corporate rebranding and the October spin-off of its automotive business to Gentherm, Modexus presented a recast multi-year financial framework to Wall Street. Management projects total company revenue to reach between $5.7 billion and $7.7 billion by fiscal 2029, propelled by a 60% to 80% annual surge in its core Data Centers division.
The data center cooling segment alone is slated to generate $4.5 billion to $6.5 billion in revenue by fiscal 2029, while Commercial HVAC is pegged for steady 7% to 10% annual expansion. Modexus also guided for consolidated adjusted EBITDA margins to reach 19% to 21% by fiscal 2029—with data center margins climbing to 22% to 24%. To underscore balance sheet confidence, the board authorized an immediate, open-ended $500 million share repurchase program. Shares of MOD gained 6.3% to close at $137.88 on Tuesday, with trading active through Wednesday and Thursday as full details crossed market wires.
Why it matters
The update crystallizes Modexus’s complete pivot from a century-old industrial radiator maker into a high-margin data center infrastructure pillar. With hyperscalers deploying power-intensive clusters, traditional air cooling is reaching physical limits, accelerating demand for modular chillers, liquid cooling distribution units, and precision air handlers.
By shedding its capital-intensive auto parts arm, Modexus has fortified its Quality and Economic Moats across advanced thermal engineering. The projected 60% to 80% data center CAGR indicates management's conviction that structural AI hardware demand will persist for years. Meanwhile, the $500 million buyback authorization—representing roughly 7% of the firm's equity value—demonstrates that aggressive manufacturing expansion can coexist with disciplined shareholder capital returns.
What to watch next
- Order backlog: Book-to-bill trends and liquid cooling contract awards from tier-1 hyperscalers.
- Margin execution: Progress toward the 22% to 24% segment EBITDA targets as new manufacturing capacity ramps.
- Buyback cadence: Pace of initial share repurchases under the new $500 million authorization.
- Q3 Fiscal 2027 results: The next quarterly scorecard and operational update in late January.
Sources (2)
This analysis is for information only and is not investment advice. Prices and figures as of publication.