Saputo Bets C$600M on High-Protein Dairy Network to Drive C$140M EBITDA Surge
Saputo pledges C$600M to expand high-protein dairy capacity across FY27–FY28, targeting C$140M in incremental annual EBITDA as shares rise to C$46.25.
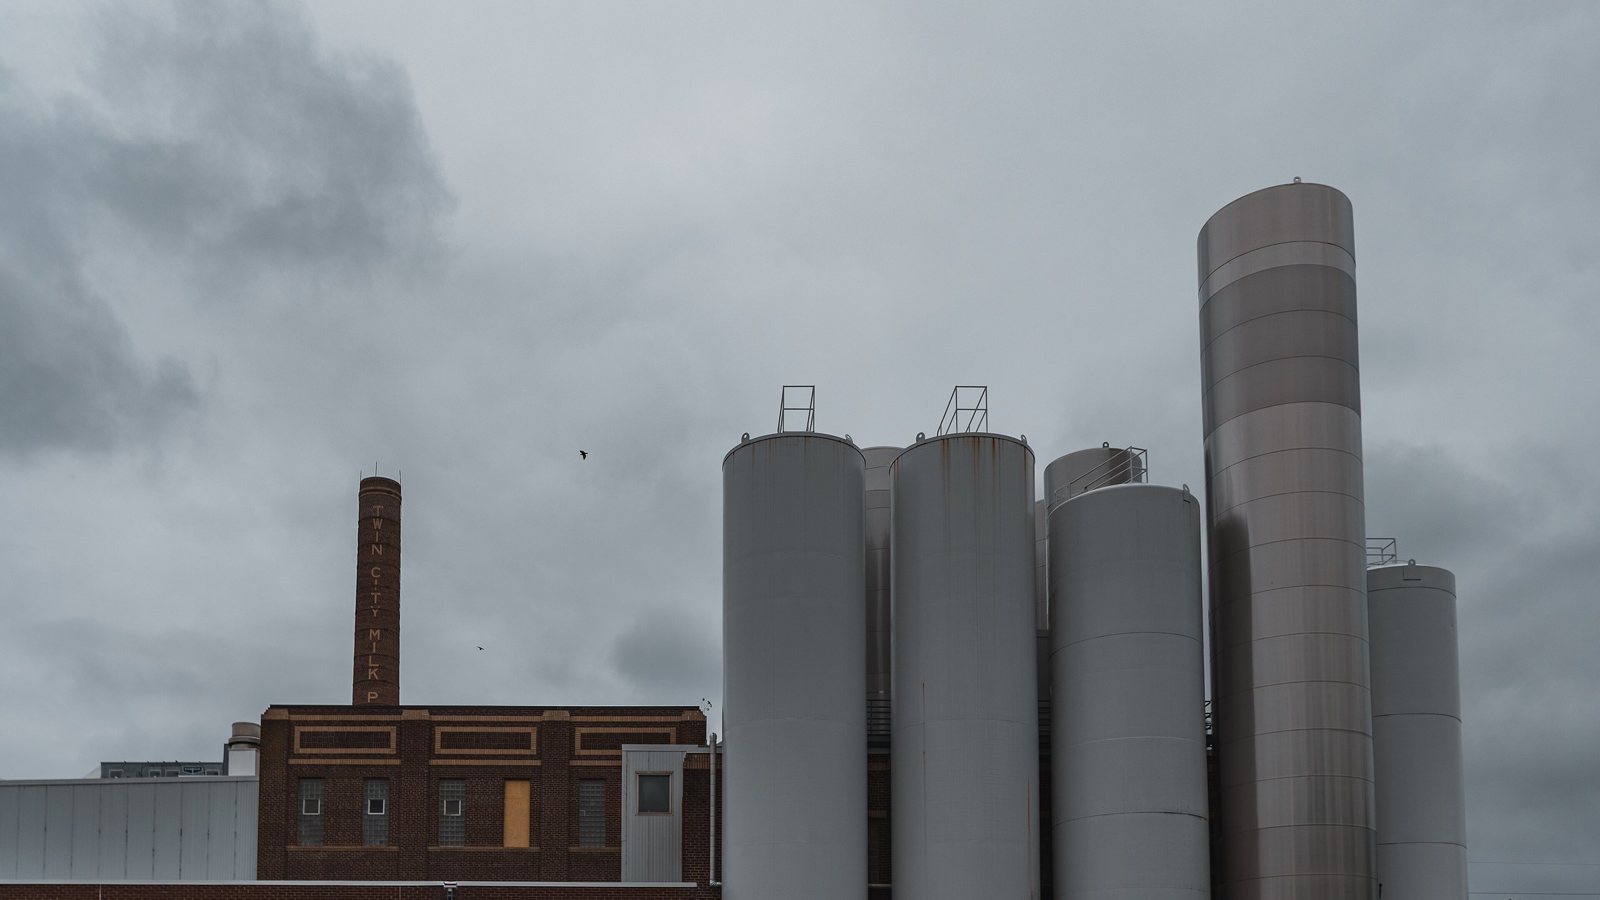
Canadian dairy titan Saputo announced a C$600 million capital investment program on Thursday to massively expand its manufacturing footprint across high-protein dairy and functional beverages over fiscal 2027 and 2028. For investors, the ambitious pivot temporarily compresses free cash flows to capture structural consumer shifts and unlock a projected C$140 million in incremental annual EBITDA by fiscal 2029.
What happened
Crossing market wires on Thursday, November 19, 2026, Saputo (TSX: SAP) revealed a multi-year capex initiative targeting rapid capacity expansion in supply-constrained categories: cottage cheese, functional beverages, high-protein dairy products, and cream cheese. The outlays will be concentrated across fiscal 2027 and 2028, with initial production ramp-up scheduled for fiscal 2029.
Under Chief Executive Officer Carl Colizza, the program builds on momentum from Saputo’s recent Q2 fiscal 2027 results, where adjusted EBITDA climbed 14% year-over-year to C$438 million and margins widened 90 basis points to 10.3% on high-protein ingredient pricing. In early trading on the Toronto Stock Exchange on Friday, Saputo shares gained 1.6% to C$46.25, hovering near 52-week highs, while the company's renewed share buyback program covering up to 10% of its public float took effect on November 19.
Why it matters
The dairy industry is undergoing a structural realignment as mainstream consumer diets favor high-protein nutrition, mirroring trends seen across packaged food leaders like BellRing Brands. Traditional commodity cheese blocks and fluid milk have suffered from volatile wholesale margins, making specialized dairy ingredients—such as whey protein concentrate (WPC 80)—a far more resilient profit driver.
However, allocating C$600 million over two fiscal years will visibly alter Saputo’s income statement and cash flow. While capital expenditures will restrain near-term free cash flow conversion, management's projected C$140 million in incremental EBITDA represents a return profile of roughly 23% on invested capital at full run-rate. If executed cleanly, the move deepens Saputo’s economic moat against generic private-label commoditization by embedding the processor into proprietary supply chains for fast-growing functional beverages.
What to watch next
- Capex cadence: Tracking quarterly capital expenditure run-rates through fiscal 2027 to ensure project buildouts remain on budget.
- Cash flow and leverage: Net debt-to-EBITDA ratios as free cash flow absorbs the C$600 million buildout alongside dividend commitments.
- Ramp-up milestones: Initial facility commissioning and customer volume commitments in early fiscal 2029 to validate the C$140 million EBITDA target.
Sources (3)
This analysis is for information only and is not investment advice. Prices and figures as of publication.